The severe financial convulsion known as the Panic of 1907 swept through the American economy, triggering cascading bank runs and widespread business failures. The crisis laid bare a critical structural deficiency: the United States had no central banking authority capable of stabilizing the nation’s credit system. In the aftermath, Washington moved deliberately to address the gap.
The National Monetary Commission, chaired by Senator Nelson Aldrich, traveled to Europe to study the central banking models of established powers. Their findings culminated in the Aldrich Plan in 1910, a proposal that set the stage for a protracted political battle over the shape of American monetary governance.
After years of debate, President Woodrow Wilson signed the Federal Reserve Act into law on December 23, 1913, formally creating the Federal Reserve System as the central bank of the United States.
A Compromise Between Centralization and Regional Autonomy
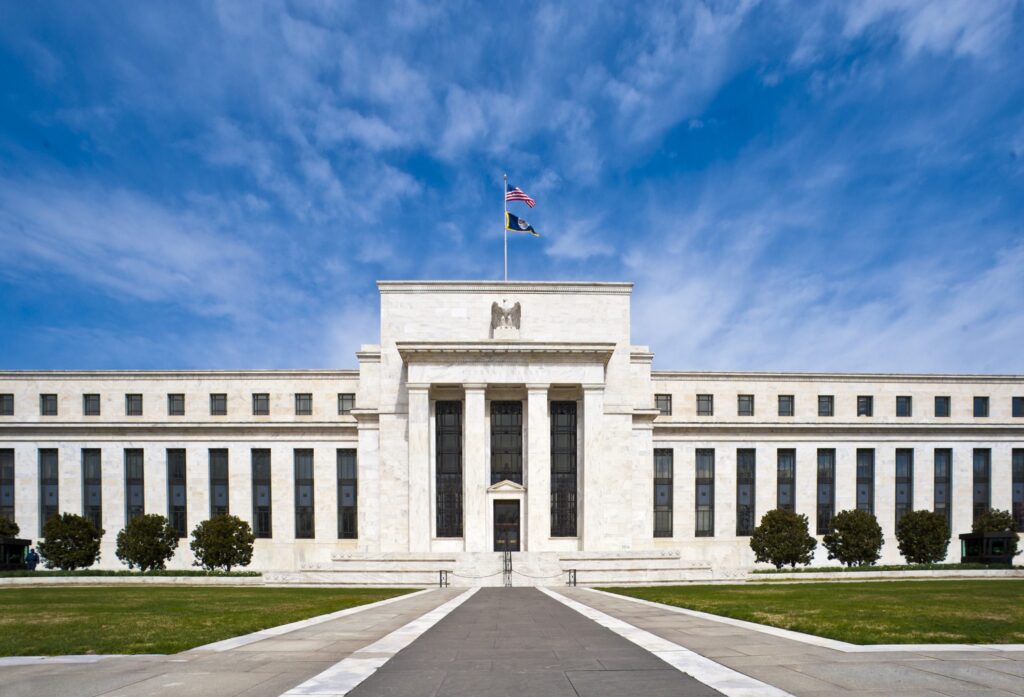
The original architecture of the Fed represented a deliberate compromise between centralized authority and regional autonomy. The system established 12 regional Federal Reserve Banks located in financial centers including New York, Chicago, and San Francisco, alongside a seven-member Federal Reserve Board based in Washington, D.C. This structure emerged from a series of financial panics that had created a sustained demand for central control over the monetary system, with the aim of alleviating future crises. The system operated as an independent entity, and its monetary policy decisions did not require approval from the president or Congress.
Over time, major events such as the Great Depression and the Great Recession would expand the bank’s responsibilities, adding duties that now include regulating banks and maintaining the stability of the financial system.
Reform and the Assertion of Independence
The Federal Reserve system did not remain static. The Banking Act of 1935 fundamentally restructured the central bank, creating the Federal Open Market Committee, or FOMC, and vesting it with formal authority over open market operations.
The calculus shifted again during World War II, when the Fed’s role expanded to help finance the war effort by maintaining low interest rates. This arrangement created a strategic tension between the central bank’s monetary policy objectives and the Treasury Department’s financing needs. The Treasury-Fed Accord of 1951 reasserted the central bank’s independence from Treasury Department control, a principle that would be tested severely in the following decades.
Inflation surged in the 1970s, peaking at 14.8 percent in March 1980. Under Chairman Paul Volcker, the Fed took drastic action, raising the federal funds rate to 20 percent in June 1981.
The move triggered a recession, but the strategic calculation paid off: inflation was eventually reduced, demonstrating the institution’s willingness to impose short-term economic pain for long-term price stability.
The Unconventional Era and the Dual Mandate
The 2008 financial crisis forced the Fed into uncharted territory. With the financial system on the verge of collapse, the central bank implemented unconventional policies that fundamentally altered its operational toolkit. The Fed bought $1.7 trillion in mortgage-backed securities and Treasury bonds through quantitative easing programs.
It also held the federal funds rate at near-zero — between 0 and 0.25 percent — from December 2008 through December 2015. Congress responded to the crisis by passing the Dodd-Frank Act in 2010, which increased the Fed’s oversight responsibilities for systemically important financial institutions.
Congress had previously assigned the bank specific objectives known as the dual mandate: maximizing employment and stabilizing prices. The Federal Open Market Committee manages these goals by adjusting the target for the federal funds rate, an action that affects market interest rates and influences general economic activity. Because the bank manages the money supply and credit, its decisions impact the cost of borrowing for most consumers and businesses across the American economy.