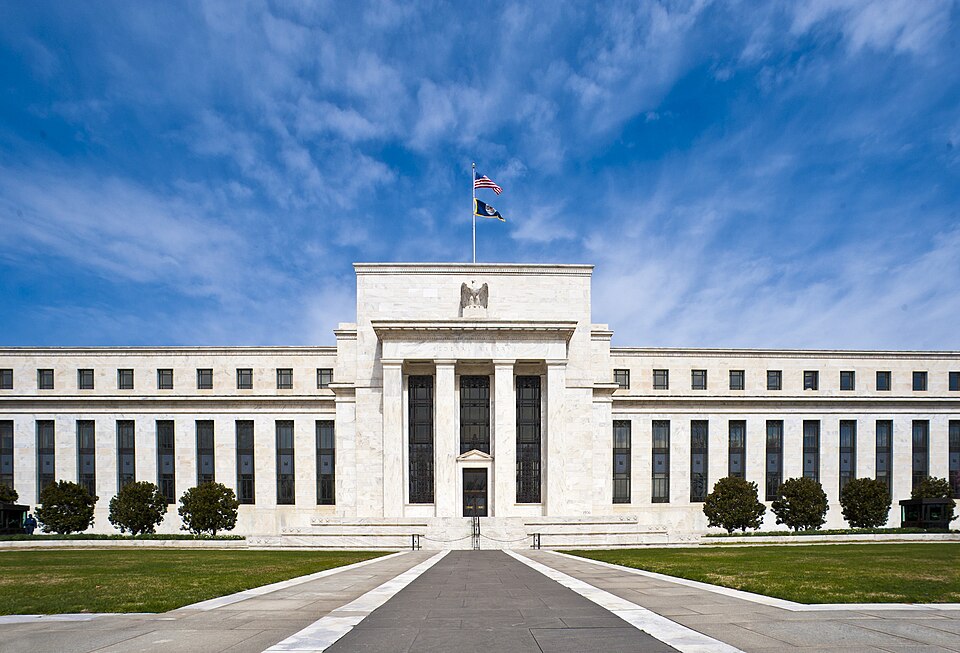
WASHINGTON, September 18 — The Federal Reserve raised its benchmark interest rate by a quarter of a percentage point in a unanimous vote, its first hike in more than three years, returning rates to levels last seen in late 2025. The mechanics here are straightforward, and that is precisely why the decision matters. Inflation is running at 3.4% annually, well above the Fed’s 2% target, and a stable job market gave policymakers the confidence that the economy could absorb the increase.
Markets were not surprised. Consumers will be.
Where the pain lands first
Scripps News financial contributor Danny Moses put the transmission channel plainly. “If you have floating rate type of loans like a HELOC, like a home equity loan, that will go up,” he said. That is the direct line from the federal funds rate to a household’s monthly payment.
But follow the money further and the picture gets more complicated. Longer-term loans — mortgages, auto loans — are tied to the 10-year Treasury yield, not the federal funds rate.
Those rates may not move as sharply. The catch is that borrowers rarely distinguish between the two when the bill arrives. Moses pointed to oil as the compounding factor.
“Oil is feeding into the inflation,” he said. “It’s a double whammy, the fact that oil goes up and hurts people’s wallet and then rates follow.”
A K-shaped economy, and who is insulated
Moses described the U.S. economy as “K-shaped,” with wealthier households largely insulated while lower-income households absorb the most pain. “Tell that to the lower-end consumer that’s already struggling at the bottom half of the K,” he said. “I completely sympathize with that.” On closer reading, the structure of household wealth has shifted in a way that matters for how this rate cycle plays out.
Moses noted that most household wealth today is concentrated in the stock market rather than home equity, as was the case during the 2006-2007 housing crisis. Higher rates, meanwhile, reward those with cash on hand.
“If you’re on the sidelines with a billion dollars, you’re earning more on your interest,” he said. “This certainly benefits wealthier people right out of the gate in terms of being able to earn a higher number that’s ‘risk-free.’” Interest rates remain 1.5 percentage points below their peak levels in late 2023 and early 2024, when the Fed raised rates aggressively in response to the highest inflation the U.S. had seen in more than two decades.
What to watch next
Moses said another hike before the end of the year is possible, putting the odds at 40% to 50%, potentially in December. He does not expect the Fed to act in the weeks immediately before the midterm elections. The path forward, he said, depends heavily on oil.
“In a perfect world, the war ends in the Middle East, oil comes down, inflation follows, and the Fed doesn’t have to raise rates anymore.” He called the hike the right call, but warned that rising fuel costs are already showing up in corporate earnings. “Whether you work at one of these companies or whether you’re struggling or whatever, I think it’s going to really have an impact on everybody,” he said.
The next data point to watch is oil — and whether December brings another quarter-point move.